Financial services and investment
Working capital where banks do not reach.
The financial arm of the group: microcredit, small-enterprise finance and selective investment, putting working capital into the traders, producers and businesses that formal banking passes over.
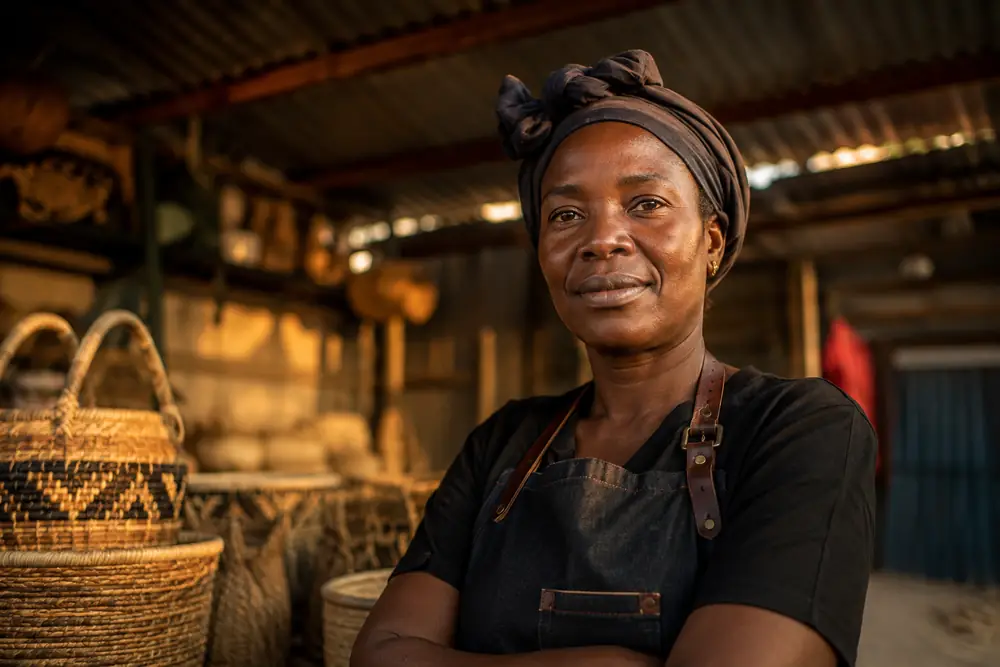
Onyx Microfinance e Investments
The binding constraint is capital access
Most economic activity in Mozambique runs through small, informal operators: market traders, transporters, smallholder farmers, family enterprises. Their constraint is rarely demand or effort; it is access to working capital on terms that match how their money actually moves.
Formal banks struggle to serve this market profitably. A lender that underwrites close to the borrower, matches repayment to real trading and harvest cycles, and keeps its cost base local can serve it well, and be repaid.
Extends the group into the domestic real economy and recycles group capital into income-generating, community-level lending and investment positions.
How the division works
Lend against real cycles
Repayment schedules follow the borrower's actual cash cycle: market days, harvests, contract payments. Not a calendar designed for salaried clients.
Underwrite up close
Credit decisions are made by people who know the market, the trade and often the borrower, with group standards behind them.
Recycle, do not extract
Returns are reinvested into the loan book and into selective stakes in productive local ventures, compounding presence rather than withdrawing it.
What Onyx Microfinance does
Microcredit
Working-capital loans from 5,000 to 500,000 meticais for traders, transporters and service businesses, with terms of up to 12 months.
Agricultural finance
Season-matched lending for smallholders and outgrowers, coordinated with Onyx Farming programmes.
SME finance
Working-capital and asset finance for established small and medium enterprises.
Selective investment
Equity and quasi-equity positions in productive ventures aligned with the group's sectors.
Who it serves
Traders and micro-enterprises
Market vendors, transporters and family businesses that need fast, right-sized capital.
Producers
Smallholders and outgrowers whose income arrives at harvest, not month-end.
Institutions and employers
Development partners and companies building financial-inclusion programmes around their people.
Working together
How an engagement starts
Eligibility conversation
A short, direct assessment of the activity, the need and the cycle.
Assessment and terms
Underwriting close to the borrower, with terms matched to real cash flow.
Disbursement and accompaniment
Capital released, then followed: repeat clients are the business model.